Selling a home in BC: what you actually keep from a $1.2 million sale
When you sell a home in British Columbia, the price on the contract isn't what lands in your bank account. Commission, legal fees, the mortgage payout, and a possible prepayment penalty come off first. On a $1.2 million sale with a $550,000 mortgage, this seller walks away with about $594,000.
This guide breaks down every deduction, shows how commission scales with price, and explains the mortgage penalty that catches many sellers off guard.
Where the money goes
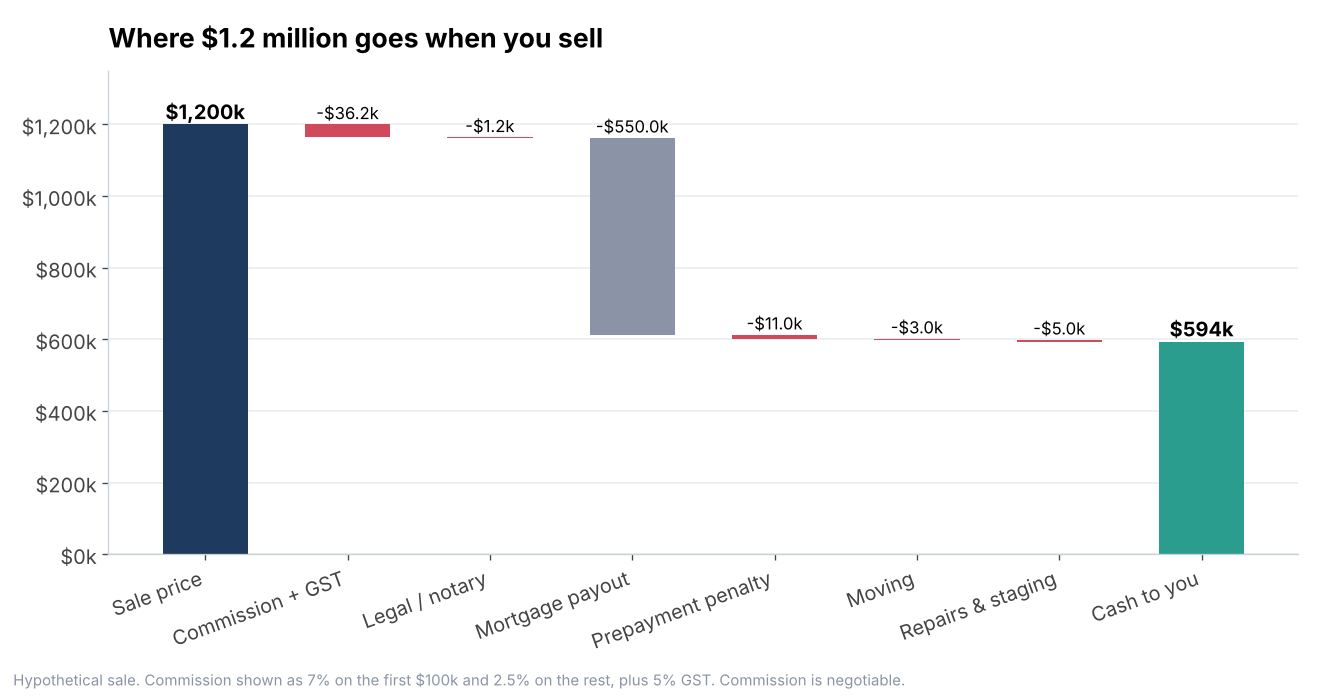
| Item | Amount |
|---|---|
| Sale price | $1,200,000 |
| Commission (7% / 2.5%) plus GST | -$36,225 |
| Legal or notary fees | -$1,200 |
| Mortgage payout | -$550,000 |
| Prepayment penalty | -$11,000 |
| Moving | -$3,000 |
| Repairs and staging | -$5,000 |
| Cash to the seller | $593,575 |
Property taxes and strata fees are adjusted to the completion date on the statement of adjustments, so a seller who prepaid the year's taxes gets part of them back.
Commission
Commission in BC is negotiable. A structure often quoted is 7% on the first $100,000 and 2.5% on the rest, and GST of 5% applies on top.
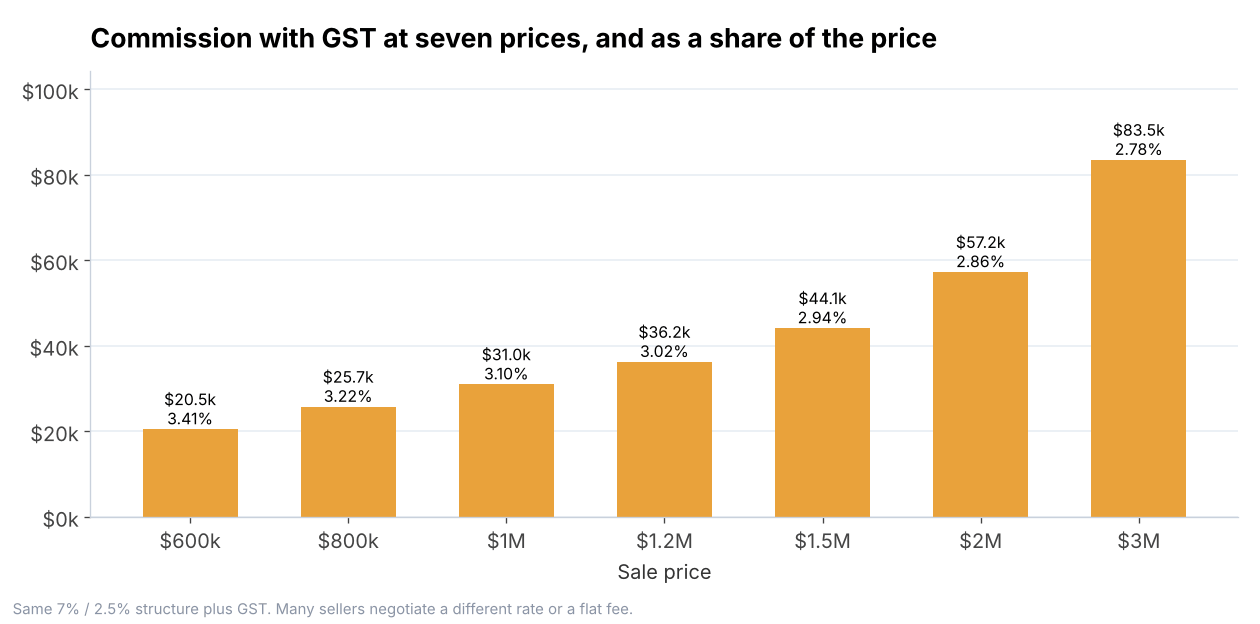
The prepayment penalty
If you break a mortgage before its term ends and don't port it to your next home, the lender charges a penalty. On a variable-rate mortgage it's usually three months' interest. On a fixed-rate mortgage it's usually the greater of three months' interest and the interest rate differential (IRD).
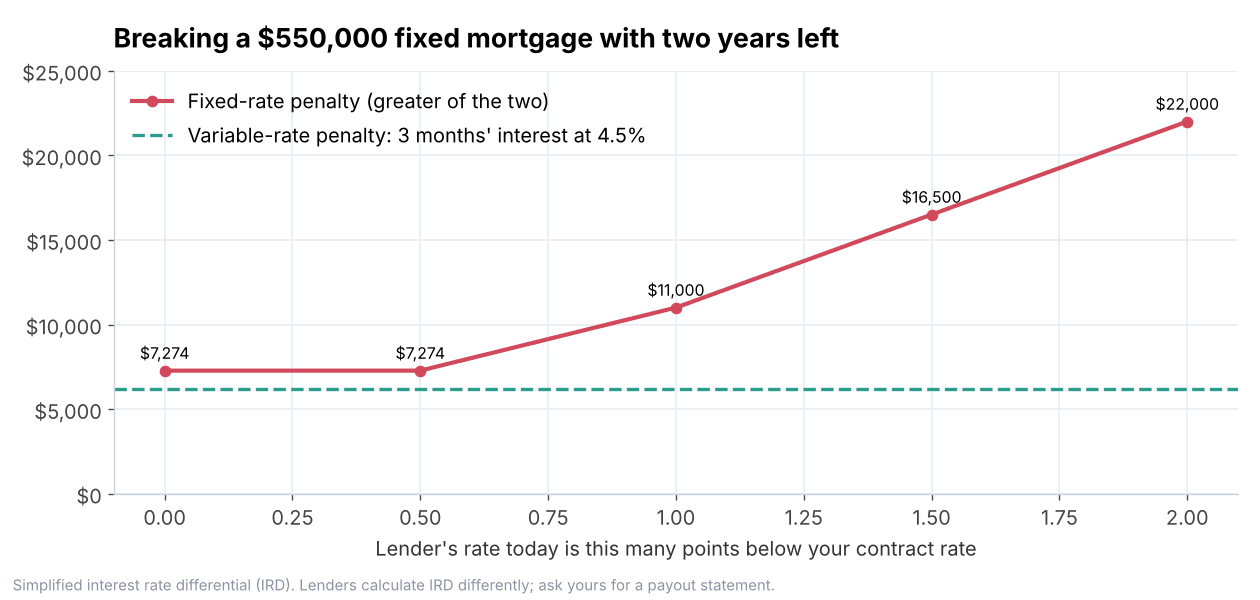
Before you list, ask your lender for a payout statement and ask whether the mortgage can be ported to your next property or assumed by the buyer.
Pricing the sale
The deductions above are fixed once you sign. The sale price is the one number you still control. Price from recent sold prices of comparable homes, not from the assessment or neighbours' asking prices. EstateBlock's guide to selling a house in Vancouver covers timing, pricing, and preparing a home for sale.
Quick answers
Do I pay capital gains tax when I sell my home? Not if the home was your principal residence for every year you owned it and you report the sale on your tax return.
When do I get the money? On completion day, after your lawyer or notary pays out the mortgage and the commission.
Sources and further reading
- Canada Revenue Agency: Sale of your principal residence
- Financial Consumer Agency of Canada: Mortgage prepayment penalties
Hypothetical figures. General information only, not legal, tax, or mortgage advice.